Things to Know Before Moving to Florida When You Haven’t Chosen a Neighborhood
Among the things to know before moving to Florida, one surprises buyers most: two homes can share the same asking price and still leave you with very different monthly bills. You might have a job offer, a target budget, or a retirement date. You might even have a few listings saved. What you probably don’t have yet is a clear way to tell which address will be easier to live with once you move in.
That gap is normal. Florida asks you to weigh things many buyers never think about elsewhere: flood maps, storm evacuation zones, insurance quotes that change by street, and fees that don’t show up in the list price. You may also be balancing commute, schools, heat, and how much you want to drive. None of these tells the whole story alone, and that makes comparing homes from far away hard.
One of the most useful things to know before moving to Florida is that the address shapes your real cost of living as much as the price does. You’ll see how to check flood and storm exposure, which insurance and fee questions to ask, how the homestead exemption works, and how to test a neighborhood against your daily routine. By the end, you can compare your shortlist on full monthly cost and fit.
Why Can Two Same-Price Florida Homes Cost Different Amounts to Live In?
The price covers the house. Your monthly cost of living in Florida also includes insurance, fees, taxes, and utilities, and each of those depends on where the house sits and how it was built.
Things to Know Before Moving to Florida: Start With the Address
Think of the list price as the first number, not the final one. Here is a hypothetical example to make it concrete.
Hypothetical: House A and House B are listed at the same price. House A sits in a high-risk flood zone and is part of a newer community with a special district fee. House B sits on higher ground in an older area with a small HOA. On paper they match. On your monthly statement, they may be far apart.
The things that split them apart are mostly tied to location:
- Flood zone and elevation, which affect flood insurance and whether a lender requires it
- Distance from the coast and storm exposure, which shape homeowners insurance quotes
- Community fees, such as homeowners association (HOA) dues or community development district (CDD) assessments
- Property taxes, which shift with local rates and your homestead status
- Home age and build features, such as roof age and storm protection
None of this means one house is better. House B might have a longer commute or fewer amenities you care about. The point is that you can’t compare two Florida homes fairly until you price both addresses.
Build a Monthly Budget Beyond the Mortgage
Your moving budget should hold every recurring cost, not just principal and interest. A simple way to start is to list each cost line for every home you’re seriously considering.
For each address, write down:
- Mortgage payment (principal and interest)
- Property taxes, with and without the homestead exemption
- Homeowners insurance quote
- Flood insurance quote, even if not required
- HOA dues and any CDD assessment
- Florida utilities estimate, including summer cooling
- Transportation costs for your real commute
Utilities deserve a closer look. Air conditioning runs for much of the year, so a home’s age, insulation, windows, and shade can change your power bill. Ask sellers for recent utility bills when you can. They show how that specific house performs, which a statewide average can’t.
Once every line is filled in, the gap between same-price homes becomes visible. That total is the number to compare.
What Should You Check About Flood and Hurricane Exposure?
Check two separate things for every address: the flood zone that drives insurance, and the evacuation zone that drives your storm plan. They overlap, but they answer different questions.
Compare Flood Zones and Elevation at Each Property
FEMA flood maps label each area by risk. An area counts as high risk when it has a 1% or greater chance of flooding in any given year, and those odds build up over the life of a 30-year mortgage.
Here is what the main zones mean in plain terms:
- Zones A and AE: high risk, often near water.
- Zones V and VE: high risk on the coast, with added danger from storm waves.
- Shaded Zone X (or B): moderate risk.
- Unshaded Zone X (or C): lower risk, though not zero.
- Zone D: risk has not been studied yet.
The A and V zones are FEMA’s high-risk areas, and FEMA says lenders require flood insurance there if you have a government-backed loan.
A lower-risk zone does not mean no risk. About 1 in 3 flood claims come from low- and moderate-risk zones. Heavy rain and poor drainage can flood streets that sit far from the coast.
Elevation adds detail the zone label can miss. Two homes in the same zone can sit at different heights. Ask for an elevation certificate if one exists, and notice whether the home sits on a raised lot or a low corner. Maps also change, so check whether an update is pending for that community.
Check the Evacuation Zone and Make a Practical Storm Plan
Evacuation zones tell you who local officials may ask to leave during a storm. Florida’s Division of Emergency Management lets you check your evacuation zone by address. Zones are lettered, with Zone A the most likely to evacuate first, and the number of zones varies by county.
This affects daily life in a calm, practical way. If your address is in an early zone, plan where you would go and how long the drive takes. If you’re outside a zone and no order is issued, sheltering at home may be an option. In that case, the strength of the house is the key question.
The state notes that homes built after 2002 generally include features that make them more resilient to hurricanes. When you tour, ask about:
- Roof age and how it is attached
- Impact windows or storm shutters
- Garage door strength
- Whether a wind mitigation inspection has been done
The state also suggests a supply kit that lasts at least seven days. Building that into your first-month plan is easier than scrambling later. A home in a later zone with storm-ready features may suit you if a smooth hurricane season ranks high. Another buyer may accept an earlier zone for a shorter commute or a lower price.
Which Insurance, Fees, and Tax Savings Change the Budget?
Insurance quotes, community fees, and the homestead exemption can move your Florida cost of living more than small price differences between homes. Get real numbers for each address before you decide.
Get Address-Specific Homeowners and Flood Insurance Quotes
Ask for quotes before you make an offer, not after. Homeowners insurance in Florida depends on the home’s location, age, roof, and storm features. Two similar homes a few miles apart can get very different quotes.
Flood coverage is separate. FEMA states that most homeowners insurance does not cover flood damage. The National Flood Insurance Program (NFIP) sells flood policies, and private options exist too. A new NFIP policy usually takes effect 30 days after purchase. FEMA’s buying guide notes there is no wait when you buy it while making, increasing, extending, or renewing a mortgage, which covers most purchases with a loan. Cash buyers should plan for the 30 days.
A few steps make your quotes more useful:
- Request quotes using the exact address and the home’s roof and window details.
- Ask whether a wind mitigation report could lower your premium.
- Ask whether the seller’s NFIP policy can be transferred to you, and compare that quote with a new policy rather than assuming the seller’s rate carries over.
- Use the Florida Office of Insurance Regulation’s rate comparison tools to see how carriers price coverage.
Compare HOA Fees With CDD Assessments
HOA dues and CDD assessments are different charges, and some homes have both. An HOA is a private association that collects dues to maintain shared spaces and enforce community rules. You pay it directly.
A CDD is a special district created under Florida law, common in newer communities. It often pays for roads, utilities, and amenities built for the area. Under state law, CDD assessments can appear on your county property tax bill. They also act as a lien on the property until paid.
When comparing homes, ask:
- What is the yearly CDD assessment, and how much is debt versus upkeep?
- When will the debt part be paid off?
- How much are HOA dues, and have they risen recently?
- Are any special assessments planned?
A CDD can fund amenities you’ll use daily, like pools or trails. If you don’t care about those, an older area without a CDD may fit better. Neither choice is wrong; it depends on what you’ll use.
Understand Homestead Exemption Eligibility Before Counting on Savings
The homestead exemption can reduce your property taxes, but only once you qualify. It works in two layers. The first $25,000 of assessed value is exempt from every property tax, school taxes included. The second layer covers assessed value above $50,000, applies to non-school taxes only, and is now indexed to inflation: the Florida Department of Revenue sets it at $26,411 for 2026.
Timing is the part that surprises new residents. You must own the home and make it your permanent residence by January 1. Then you file with your county property appraiser by March 1 of that tax year. If you close in spring, your first tax bill may not include the savings.
Budget for the first year without the exemption. Then treat the savings as a later benefit. The property appraiser may ask for proof of residency, such as a Florida driver’s license or voter registration.
Will the Neighborhood Work for Your Everyday Routine?
A good budget fit still needs to match how you’ll spend ordinary days. Living in Florida means planning around heat, driving, and access to the places you visit every week.
Test Heat, Shade, and Car Dependence on an Ordinary Day
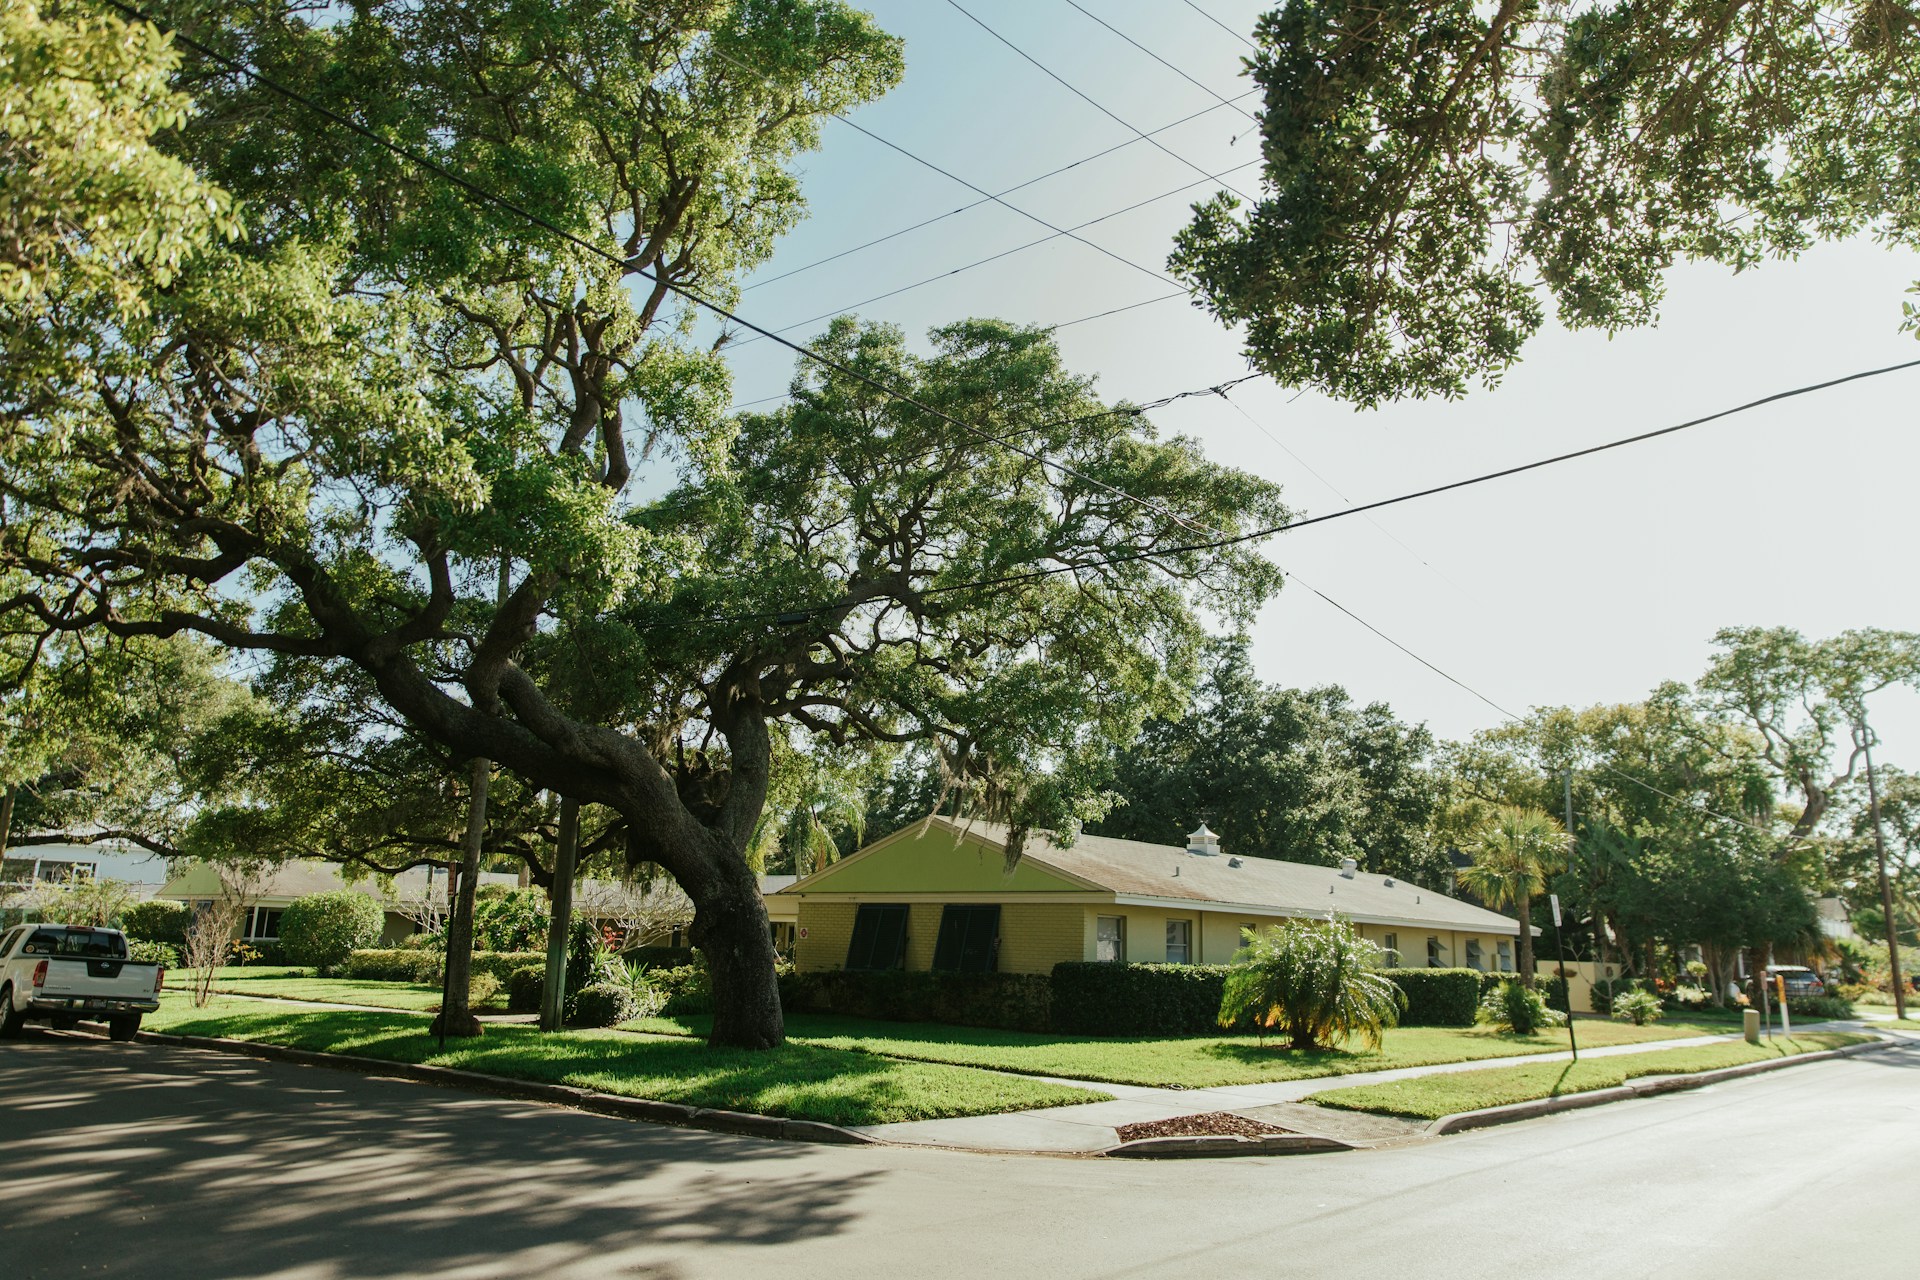
The Florida climate shapes how you use a neighborhood. A walk to a park that sounds easy in winter can feel very different on a summer afternoon. Shade, sidewalks, and distance all affect whether you’ll walk at all.
Many Florida neighborhoods are built around cars. If you want to walk or bike for errands, look closely at:
- Tree cover and shaded sidewalks
- Safe crossings on busy roads
- How far the nearest grocery store and pharmacy are
- Whether shops and services stay open when you need them
If you can visit, go in the middle of a hot day, not just in the cool morning. If you can’t, use street-level map views to check sidewalks and shade. A buyer who drives everywhere may care little about these details. A buyer who wants to drive less, or who may stop driving later, will weigh them much more.
Check Actual Commutes, School Assignments, and Nearby Services
Test the commute at the hours you’ll drive it. A short route on the map can stretch at rush hour or during peak tourist season. Run directions for a weekday morning and evening from each address on your list.
For Florida schools, check the assigned school for the exact address. Boundaries can split a neighborhood. The Florida Department of Education offers a school mapping tool that shows public school grades by district or distance. Confirm the attendance zone with the school district before you make an offer, since boundaries can change.
If you’re looking at the two Florida metros with neighborhood guides, compare safety data in Orlando neighborhoods and Orlando school options. Miami buyers can review Miami neighborhood safety alongside Miami school data. Treat each as one input next to your commute and budget.
Also map the services you’ll use: doctors, urgent care, groceries, and pharmacies. A home with a lower monthly cost may still be the wrong fit if every errand takes 25 minutes each way.
What Should You Verify Before Making an Offer?
Before you offer, confirm the full monthly cost and the key property facts for each finalist. This step turns your Florida relocation checklist into a side-by-side decision.
Compare the Full Monthly Cost of Your Shortlisted Addresses
Put your finalists side by side using the budget lines from earlier. Use real quotes, not guesses, wherever you can. Then add the costs that come from location:
- Commute fuel and time
- Insurance, including flood coverage
- HOA and CDD charges
- Property taxes for year one, before homestead savings
Look at the gap between the highest and lowest total. If a slightly higher-priced home costs less each month, it may be the better budget choice. If the lower-cost home adds an hour of driving each day, you’ll have to decide what that time is worth to you.
Confirm Property Details Before You Commit
Good Florida neighborhood research before buying includes a few property checks. Ask for or confirm:
- The flood zone and any elevation certificate
- Roof age and the wind mitigation report
- Seller disclosures about past flooding or storm damage
- HOA rules, budget, and any planned special assessments
- CDD assessment amounts and payoff timeline
A local agent can help you get these documents quickly. You can browse a vetted agent directory to find one who knows the area.
The Address Matters More Than the Asking Price
The home you can afford and the home you can afford to live in are two separate numbers in Florida. Flood zone, insurance, fees, taxes, and daily routine all depend on the address. Pricing each one is how you find the true gap between homes that look alike online.
That gap is where many moves go wrong. “Seventy percent of people regret their move. That’s not a housing-market problem. That’s a decision-support problem, and nobody was solving it,” says SettleSavvy co-founder Brigham Redd.
Your priorities decide what to do with that gap. A buyer focused on storm readiness may pay more for a newer, higher home. Another may accept higher insurance for a short commute or a walkable street. Both choices can be sound when you make them with clear numbers.
Once you have priced a few addresses, a free SettleSavvy map can help you find Florida neighborhoods that fit your budget lines and daily routine. If you would like help reading the numbers, you can connect with a Savvy Consultant.
Frequently Asked Questions
What Costs Do New Florida Homeowners Overlook Most?
The usual surprises are flood insurance outside high-risk zones, CDD assessments that arrive on the property tax bill, higher summer power bills, and a first-year tax bill that does not yet include homestead savings. Price each one for the exact address before you compare homes on list price.
How Much Money Should I Have Before Moving to Florida?
Plan for your down payment and closing costs, plus moving costs and a cash cushion for the first months. In Florida, also set aside money for insurance premiums due at closing and a storm supply kit. Budget your first year of property taxes without the homestead exemption, since you may not qualify right away.
What Is the Biggest Property-Related Risk to Check Before Buying in Florida?
Flood exposure is the risk to check first, because it affects both your safety and your insurance cost. Look up the flood zone, ask about elevation and past flooding, and get a flood insurance quote even outside high-risk zones. Then check the home’s storm features, such as roof age and window protection.
Does Living in Florida for Six Months Qualify Me for the Homestead Exemption?
No, six months is not the homestead test. You must own the home and make it your permanent residence by January 1, then file with your county property appraiser by March 1.
How Can I Compare Florida Neighborhoods if I Can’t Visit Before Making an Offer?
Use address-level tools for flood zones, evacuation zones, and assigned schools, and run commute directions at your real travel times. Street-level map views can show sidewalks, shade, and nearby services. A local agent can also walk the street for you, take video, and gather documents like elevation certificates.